
Double Taxation: Practical Tips for Businesses Operating Internationally
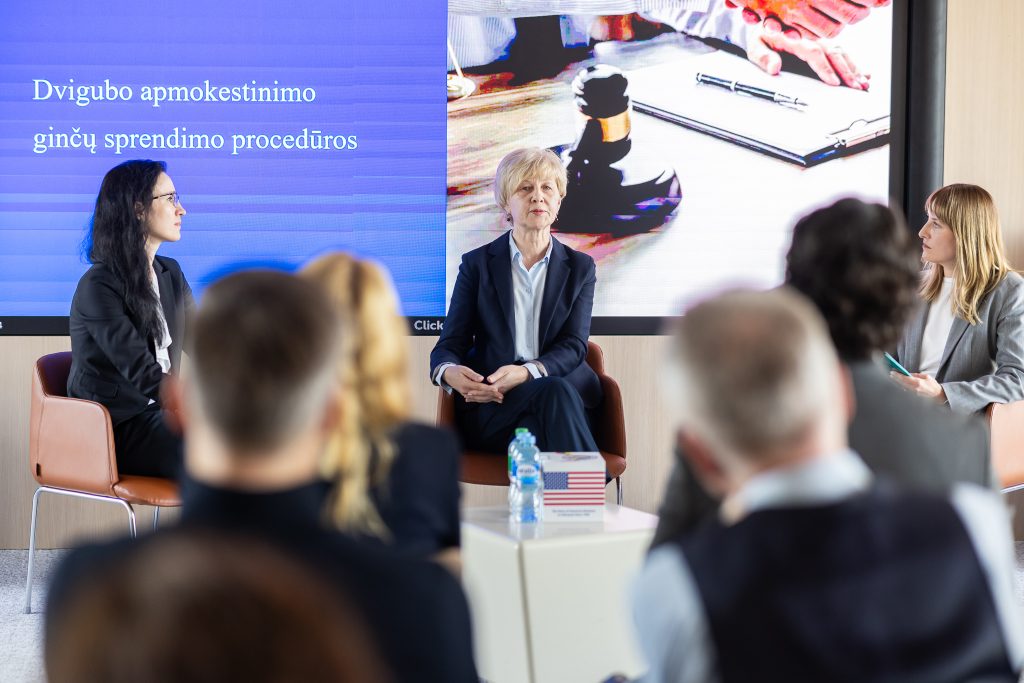
Just recently, the American Chamber of Commerce in Lithuania hosted a tax seminar featuring Rokas Daugėla (COBALT Partner) and Rasa Mikutienė (COBALT Associate Partner), joined by guest speakers Vaidė Riškutė and Rūta Varkauskienė, respectively the head and the member of the Permanent Working Group for Double Taxation Dispute Resolution Procedures (Nuolatinė darbo grupė dvigubo apmokestinimo ginčų sprendimo procedūroms vykdyti) established by the State Tax Inspectorate (VMI).
The Double Taxation Problem
International businesses and mobile executives regularly face situations where the same income is taxed twice – once in the country of residence (which taxes worldwide income) and again in the source country (which taxes income earned within its borders). Tax treaties and domestic law provide mechanisms to eliminate this burden, typically through exemptions or foreign tax credits.
The seminar explored common risk areas, particularly for companies with internationally mobile executives. Key takeaways included the importance of accurately documenting work locations, properly allocating compensation across jurisdictions, and separately tracking different income types such as salary, bonuses, and board fees.
US-Specific Considerations
The seminar also addressed specific challenges arising from investments and activities connected with the United States.
First, the speakers noted that the taxation of returns on investment into different types of US entities can vary significantly. In particular, structures involving partnerships and limited liability companies (LLCs) may give rise to double taxation issues due to differences in how these entities are characterized under US and foreign tax regimes. As a result, careful structuring of such investments is essential to minimize unintended tax consequences.
Second, US citizens working abroad face unique double taxation challenges, as they remain subject to US tax on worldwide income regardless of where they reside. Proper tax planning is therefore critical to mitigate these risks, particularly when compensation includes share-based incentives or other non-cash instruments, which can create complex timing and sourcing issues across multiple jurisdictions.
Discussion with VMI representatives
A highlight of the seminar was the discussion with VMI representatives on what happens when double taxation cannot be eliminated through standard tax returns or adjustments – typically because two countries interpret the same situation differently.
In such cases, taxpayers can turn to the Mutual Agreement Procedure (MAP) – essentially a negotiation process between the competent authorities of the states involved. MAP can be initiated either under the applicable double tax treaty or within the EU legal framework.
The EU framework offers an important advantage: it guarantees the elimination of double taxation in all eligible cases. If the competent authorities cannot reach an agreement, the matter proceeds to a special commission with an arbitration function, ensuring a binding resolution, except for certain ineligible cases (e.g., when the three-year initiation period is missed, or when the situation involves incorrect application of the treaty but does not result in actual double taxation, and certain others).
The message from the tax authorities was clear: taxpayers should not give up. MAP is an underutilized but powerful tool, and those facing unresolved double taxation should actively pursue it to achieve full relief.
About the Speakers
Rokas Daugėla is a Partner at COBALT, and Rasa Mikutienė is an Associate Partner at COBALT, both specializing in international taxation.
For more information, contact: Rokas.daugela@cobalt.legal, rasa.mikutiene@cobalt.legal.