
The AmCham Business Environment Committee’s White Paper on the
Strategic Benefits of Listing State-Owned Enterprises
One of the key missions of the American Chamber of Commerce in Lithuania (AmCham Lithuania) is to serve as a leading voice for American and international businesses in the country. A great example of this is the AmCham Business Environment Committee, which published a White Paper highlighting the strategic benefits of listing state-owned enterprises.
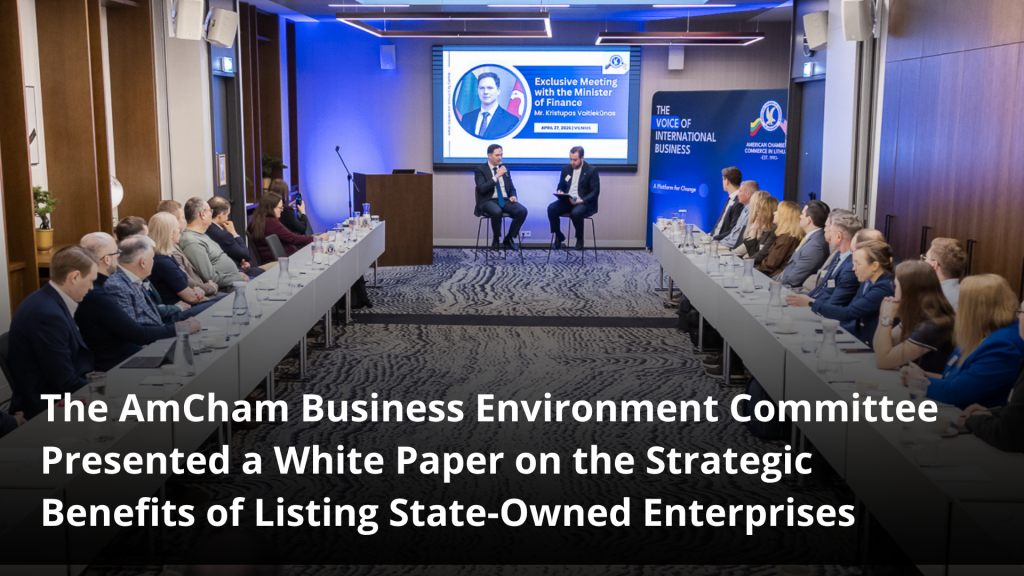
The white paper was presented and discussed during a meeting between the American Chamber of Commerce in Lithuania members and the Minister of Finance, Mr. Kristupas Vaitiekūnas. Through this initiative, AmCham explores ways to improve Lithuania’s business environment.
Executive Summary
The strategic listing of state-owned enterprises (SOEs) represents a critical opportunity for Lithuania to strengthen its capital markets, enhance economic competitiveness, and attract both domestic and international investment. This white paper examines the rationale for public listings of SOEs, identifies key challenges in the current system, and provides comprehensive recommendations for implementation. By bringing state-owned companies to public markets, Lithuania can improve corporate governance, expand access to capital, foster investment culture, and position itself for inclusion in higher-tier of MSCI investment index that would multiply institutional investment flows from thousands to millions of euros.
Key Highlights
Challenges in the Current State Ownership Structure
1. Excessive State Participation in Business: Lithuania ranks among the top European countries for state participation in business activities. Many state-owned companies operate in sectors where private enterprise could function effectively, raising questions about the necessity and extent of state ownership.
Recommendation: Adopt partial strategic listings (30–70%) to reduce unnecessary state ownership while preserving control where needed. This approach ensures state oversight but brings market discipline, transparency, and investor participation.
2. Limited Capital Market Development: The current structure restricts companies’ access to diverse funding sources, forcing reliance on state budget allocations and limiting growth potential. This dependency creates vulnerabilities during economic downturns and constrains strategic development initiatives.
Recommendation: Enable SOEs to access equity and debt markets through listing, reducing dependence on state funding and improving financing terms via increased investor confidence and regulatory oversight.
3. Opportunities to Enhance Transparency and Strengthen Performance Accountability: State ownership often results in reduced transparency and weaker performance oversight compared to publicly listed companies. Without market scrutiny, management quality and operational efficiency may suffer.
Recommendation: Subject SOEs to market scrutiny, analyst coverage, transparent reporting, and market‑based KPIs. These measures raise management quality, reduce political involvement, and create long‑term shareholder value.
4. Missed Investment Opportunities: The current system fails to provide Lithuanian citizens and pension funds with meaningful investment opportunities in national enterprises, limiting wealth-building potential and investment culture development.
Recommendation: Use SOE listings to create broad access to national ownership, encourage long‑term savings, and support dividend‑paying investment products. Baltic countries can build on a fast‑growing retail base now exceeding 300,000 investors.
5. Insufficient Foreign Investor Interest: The absence of large, stable Lithuanian companies on public markets reduces international investor attention, limiting capital inflows and broader economic benefits.
Recommendation: Position major SOE listings as anchor investments that draw institutional capital and create spillover effects for other companies in the ecosystem. This improves financing conditions, job creation, and Lithuania’s overall investment profile.
6. Limited Capacity to Strengthen Regional Security and Defence Financing
Recommendation: Leverage the listing of strategically important SOEs to unlock additional capital, strengthen economic resilience, and create sustainable long‑term funding channels that support national defence priorities and regional security.
7. MSCI Index Classification Challenges: The lack of substantial listed companies prevents Baltic countries from advancing from frontier to emerging markets status in MSCI classifications, significantly limiting institutional investment potential.
Recommendation: Prioritize listing large SOEs capable of reaching €2.25B+ market capitalization, a key requirement for MSCI Emerging Markets status. Achieving reclassification can multiply institutional flows from thousands to millions.
___________________________________________________________________________________________________________________________________________________________________________
READ THE FULL WHITE PAPER HERE>>
___________________________________________________________________________________________________________________________________________________________________________
Detailed Highlights and Recommendations
1. Challenge: Excessive State Participation in Business
Recommendation: Implement Strategic Partial Listings of Major State‑Owned Enterprises
Addressing the challenge of excessive state participation requires a structured and transparent approach to determining where state ownership remains essential and where market participation can deliver greater value. The starting point is a thorough assessment of each enterprise to evaluate whether state ownership is necessary and what level of state shareholding is optimal. In many cases, partial public listings—typically in the range of 30–70 percent—offer the most balanced solution. This model allows the state to maintain strategic control where national interests require it, while still introducing the benefits of market discipline, broader oversight, and diversified ownership.
Enterprises selected for listing should demonstrate solid operational performance, clear strategic relevance, and readiness for public‑market standards. Ensuring a transparent listing process is essential: valuations must be fair, investor access equal, and communication open, creating trust both domestically and internationally. When implemented through the stock exchange, the process gives the government the tools to manage ownership distribution in a controlled and efficient manner, while enabling capital inflows that reduce pressure on the state budget.
Practical evidence already exists within Lithuania. The Ignitis Group has shown that state‑owned enterprises can operate successfully as publicly traded companies without compromising national interests. International experience further reinforces this point: Sweden’s approach with Telia—where the state retains a 37 percent stake—demonstrates how partial state ownership combined with public listing can deliver strong value for both the state and private investors.
Similar success stories can be found globally. Many internationally recognized companies began as state‑owned enterprises and expanded into competitive multinational brands after adopting market‑based governance models. Companies such as DHL and DPD, which originated within state postal or logistics structures, illustrate how gradual commercialization, operational autonomy, and private‑sector participation can unlock global scale, innovation, and professional management while maintaining the state’s strategic interests during the transition.
This model illustrates that strategic oversight and public‑market performance can coexist effectively, providing a proven blueprint for Lithuania’s own SOE transformation.
2. Challenge: Limited Capital Market Development
Recommendation: Enable SOEs to Access Equity and Debt Markets Through Public Listing
Enhancing access to diversified funding sources is essential for reducing SOEs’ dependence on state budgets and enabling long‑term strategic growth. Listing state‑owned enterprises significantly expands their ability to raise capital by opening access to both equity and debt markets, allowing companies to issue shares and bonds to a broad base of domestic and international investors. This broadened financing capacity supports modernization, strategic investment programs, and large‑scale expansion initiatives that would otherwise rely heavily on the state budget.
A common political concern is that listing state‑owned enterprises could lead to higher prices for citizens if companies begin prioritizing profitability. This risk can be effectively mitigated by maintaining majority state ownership in strategic sectors and applying strong regulatory oversight to ensure that essential services remain accessible and affordable. Importantly, the greater transparency, efficiency, and financial discipline associated with public‑market participation can reduce long‑term taxpayer costs by improving SOE performance and decreasing reliance on direct budget financing. This, in turn, contributes to a more resilient fiscal foundation that supports the state’s capacity to provide targeted social protection to vulnerable populations.
As publicly listed entities, SOEs benefit from the enhanced confidence of investors, strengthened by regulatory oversight and increased transparency, which often leads to improved financing terms and a lower cost of capital. The experience of Nordic countries demonstrates that well‑managed listed state enterprises frequently secure more favorable financial conditions than fully state‑owned entities, as market discipline drives stronger financial performance, better governance, and more effective risk management.
Based on the Nordic experience, several listed state-owned enterprises demonstrate how market discipline enhances financial performance and governance. Equinor, with 67% Norwegian state ownership and dual listing on Oslo and New York exchanges, has achieved significantly lower borrowing costs than comparable fully state-owned national oil companies while maintaining world-leading transparency standards and successfully transitioning into renewable energy under investor scrutiny. Similarly, Finland’s Fortum, approximately 51% state-owned and listed on Nasdaq Helsinki, has leveraged access to international capital markets to fund its renewable energy expansion at competitive rates while market discipline forced strategic asset optimization and professional risk management frameworks. Telia Company, jointly owned by the Swedish and Finnish governments and listed on Nasdaq Stockholm, underwent major governance reforms following corruption scandals, with shareholder pressure driving the divestment of underperforming assets and improved capital efficiency that resulted in better credit ratings and substantially lower cost of capital compared to state telecom monopolies. These examples illustrate that partial listing—typically maintaining state ownership between 40-70%—creates optimal conditions where quarterly reporting requirements, independent board oversight, and investor expectations drive operational efficiency and financial discipline while preserving the state’s strategic influence and public policy objectives.
3. Challenge: Limited Transparency and Weak Performance Accountability
Recommendation: Strengthen Governance Through Market Scrutiny and Transparent Reporting:
To illustrate how transparency and performance accountability improve under a public‑market model, it is useful to consider the practical effects that listing has on state‑owned enterprises. When a company becomes publicly traded, its management is subject to continuous scrutiny from analysts, investors, and regulators. While many state‑owned enterprises already operate with clear public mandates, their performance frameworks can sometimes prioritize stability and service continuity over more ambitious, market‑driven targets. Introducing public‑market requirements helps complement these existing strengths by encouraging the adoption of more rigorous KPIs and stretch goals that support innovation, efficiency gains, and long‑term strategic development.
Market‑based performance incentives encourage leaders to focus on efficiency, long‑term value creation, and sound strategic decision‑making. Importantly, the listing process also minimizes political involvement in operational matters, as management decisions must be justified to the market rather than to shifting non-balanced priorities.
Lithuanian examples, such as Ignitis Group, already demonstrate how public‑market expectations elevate governance quality and strengthen overall accountability, creating a more transparent, predictable, and performance‑driven operating environment.
4. Challenge: Missed Investment Opportunities for Citizens and Pension Funds
Recommendation: Expand National Investment Access and Strengthen Retail Investor Engagement
Developing an investment culture in Lithuania requires widening access to national economic assets and ensuring that citizens and pension funds can participate meaningfully in the country’s long‑term growth. Listing state‑owned enterprises enables individuals to become co‑owners of nationally important companies, allowing them to build wealth through dividend income and capital appreciation while contributing directly to the country’s economic development. This approach expands opportunities not only for Lithuanian retail investors but also for pension funds, which gain access to more diversified, higher‑quality local investment instruments aligned with long‑term savings goals.
The growing Baltic retail investor base—now exceeding 300,000 participants—demonstrates strong public appetite for accessible and transparent investment opportunities. By listing SOEs and ensuring they offer clear dividend policies, transparent reporting, and accessible investment channels, the state can significantly accelerate the development of a broad, stable investor community.
International examples, such as Sweden’s population‑wide investment participation where nearly 70 percent of households invest in markets, show how democratized ownership strengthens both economic resilience and public trust.
Importantly, listing state-owned companies can serve as a powerful tool to attract investment from the Lithuanian diaspora living abroad, creating an emotional and economic connection between expatriate Lithuanians and their homeland’s economic development. This diaspora engagement can bring significant capital inflows while strengthening cultural and economic ties with Lithuanian communities worldwide.
5. Challenge: Insufficient Foreign Investor Interest
Recommendation: Use SOE Listings as Anchor Investments to Attract International Capital
Taking shares of large and stable state‑owned enterprises to the stock exchange is one of the most effective ways to attract attention and capital from international investors. When sizeable SOEs are listed, global institutional funds gain a credible entry point into a market they may have previously overlooked. These companies become anchor investments that increase visibility not only for the enterprises themselves but for the entire Lithuanian capital market. The presence of strong, publicly traded SOEs creates spillover effects that benefit both listed and unlisted domestic companies by improving financing conditions, encouraging equity research, and expanding the overall depth of the market.
Listing major SOEs also strengthens Lithuania’s position as an investment destination within the Baltic region. Increased foreign investor participation improves liquidity, enhances valuation standards, and raises the profile of the local market internationally. The Swedish experience, where a dynamic listing culture has supported more than 500 IPOs over the past decade, illustrates how active public markets can stimulate investment flows, support innovation, and promote broader economic growth. Lithuania has already seen this effect through the Ignitis Group listing, which attracted significant international interest and demonstrated how a well‑prepared SOE can serve as a catalyst for greater foreign investment across the economy
Taking shares of large and stable state-owned companies to the stock exchange helps attract attention and capital from international investors to Lithuania, improving financing conditions for other ambitious local companies and creating a favorable environment for economic growth and job creation. The spillover effect means that funds investing in newly listed state-owned enterprises often expand their exposure to other listed and unlisted Lithuanian companies, amplifying the positive impact on the entire business ecosystem. This increased international attention not only enhances Lithuania’s profile as an investment destination and leads to improved access to capital across the economy, but also raises the region’s visibility and strategic importance, contributing to greater economic and geopolitical security.
The Swedish experience, with more than 500 initial public offerings over the past decade, demonstrates the vibrancy that active capital markets can bring to a national economy, supporting innovation, entrepreneurship, and economic diversification.
The Ignitis Group listing demonstrated how such strategic moves can attract significant international attention and investment, creating positive spillover effects for other Lithuanian companies and the broader capital market ecosystem.
6. Challenge: Limited Capacity to Strengthen Regional Security and Defence Financing
Recommendation: Leverage SOE Listings to Support Strategic Investments and Enhance Economic Resilience
Strengthening regional security increasingly depends on the ability of states to finance long‑term defence capabilities, maintain resilient economies, and reduce vulnerability to external pressures. Lithuania’s current state‑ownership model limits the financial flexibility of major enterprises whose contributions could otherwise reinforce national priorities. By listing selected state‑owned enterprises, the government can unlock substantial additional capital—both domestic and international—while preserving strategic control. This expanded capital base enables the state to allocate budget resources more efficiently, prioritizing defence and security investments without overburdening taxpayers or compromising fiscal stability.
Publicly listed SOEs also operate under higher standards of governance, transparency, and risk management, reducing opportunities for political interference and strengthening overall institutional resilience. Companies that meet global governance expectations are better positioned to participate in international infrastructure, cybersecurity, and energy‑security projects that have direct relevance to national defence. A stronger, more transparent corporate sector also enhances investor confidence, which in turn increases the nation’s economic resilience—an increasingly important dimension of modern security architecture.
Additionally, SOE listings broaden Lithuania’s visibility among global institutional investors, some of whom specialise in allocating capital to stable, strategically important sectors such as energy, telecommunications, and critical infrastructure. Increased foreign institutional participation not only enhances market depth but also contributes to long‑term economic stability—an essential factor in supporting defence spending commitments, NATO capability targets, and rapid‑response financing needs. In this way, SOE listings become a strategic tool that links economic development with national security, strengthening Lithuania’s ability to sustain defence investments and contribute robustly to regional stability.
7. Challenge: Limited Progress Toward MSCI Emerging Markets Classification
Recommendation: Prioritize Listing Large SOEs Capable of Meeting MSCI Requirements
Advancing Lithuania and the broader Baltic region toward MSCI Emerging Markets classification requires the presence of several large, liquid, and well‑governed companies that meet stringent index inclusion criteria. Currently, the region remains constrained by a shortage of sizeable listed enterprises, limiting its visibility and credibility among major institutional investors. To qualify for Emerging Markets status, the region must demonstrate a sufficient number of companies exceeding the required market capitalization threshold—approximately €2.25 billion—while ensuring adequate liquidity and free‑float levels. Large state‑owned enterprises are uniquely positioned to fulfill these requirements due to their scale, strategic importance, and potential to attract strong investor demand.
The transition from frontier to emerging markets status would have significant economic implications. Inclusion in higher‑tier indices unlocks access to global institutional capital, much of which is restricted to markets classified as emerging or developed. Importantly, more than 85 leading international institutional investors actively track and allocate capital based on MSCI classifications, meaning that index advancement would immediately expand Lithuania’s visibility to a deep pool of global capital. This shift could multiply investment flows from thousands to millions of euros, substantially boosting liquidity and improving valuation standards across Baltic exchanges. Listing major SOEs therefore becomes a strategic tool not only for enhancing the depth and resilience of Lithuania’s capital markets but also for elevating the region’s presence on the global investment map.
By prioritizing the public listing of large enterprises capable of meeting MSCI thresholds, Lithuania can accelerate progress toward reclassification and secure long‑term benefits for both the state and the private sector.
8. Supporting Measures for Lithuania’s Capital Markets
While the strategic listing of state‑owned enterprises (SOEs) is a powerful catalyst for capital‑market growth, its full impact is realized only when it is complemented by broader initiatives that support the overall market ecosystem. The increased visibility, liquidity, and investor engagement that follow SOE listings naturally correlate with the need for a stronger market infrastructure, creating a favorable environment for several key development measures.
One essential area is the Investment Account framework, where more efficient structures and targeted tax incentives would make it easier and more attractive for individuals and institutions to invest in locally listed companies. SOE listings help highlight this need by expanding the universe of investable assets and demonstrating the importance of channels that allow investors to participate seamlessly in the market.
Educational initiatives also play a critical role. As SOE listings attract new retail investors and raise public interest in the capital markets, financial‑literacy programs become even more relevant. By equipping citizens with the knowledge and confidence to invest, these initiatives broaden the domestic investor base and help foster a long‑term investment culture that can fully benefit from the opportunities created by SOE listings.
Improving and stimulating local market liquidity is another complementary priority. The presence of large, publicly traded SOEs increases trading activity and analyst attention, which in turn aligns with efforts to attract more exchange members, extend trading hours, encourage equity research, expand market‑making, and potentially introduce a local market ETF. These measures help ensure that the liquidity generated by SOE listings can be absorbed efficiently, making the market more dynamic, resilient, and accessible to both domestic and foreign investors.
Together, these complementary actions create a supportive environment in which SOE listings can deliver their full value. They address not only the supply of investable assets but also the necessary demand, infrastructure, and investor engagement required for sustainable, long‑term capital‑market development.
Conclusion
To foster economic growth and enhance competitiveness, Lithuania must prioritize creating a supportive environment for diversified financing through strategic listings of state‑owned enterprises. The experience of the Nordic countries—where governments have successfully balanced strategic state interests with the advantages offered by well‑functioning capital markets—provides a clear and relevant roadmap for Lithuania’s own development. Achieving this vision will require strong government leadership, visible commitment, and targeted policy measures that encourage capital‑market growth through SOE listings and the complementary initiatives surrounding them. Such leadership can play a pivotal role in reducing risk and making capital more accessible to businesses of all sizes.
The transformation of state‑owned enterprises through public listings, supported by broader market‑development initiatives, represents far more than a privatization strategy. It offers a comprehensive approach to national economic advancement—enhancing transparency, strengthening corporate governance, attracting international investment, and improving Lithuania’s position within global capital markets.
By adopting this proactive and integrated approach, Lithuania can unlock its full economic potential, accelerate progress toward MSCI Emerging Markets classification, engage its global diaspora in national development, and position itself as a leader in the Baltic region’s capital‑market evolution.